By Ellard Thomas, MBA · Smarter Business Growth
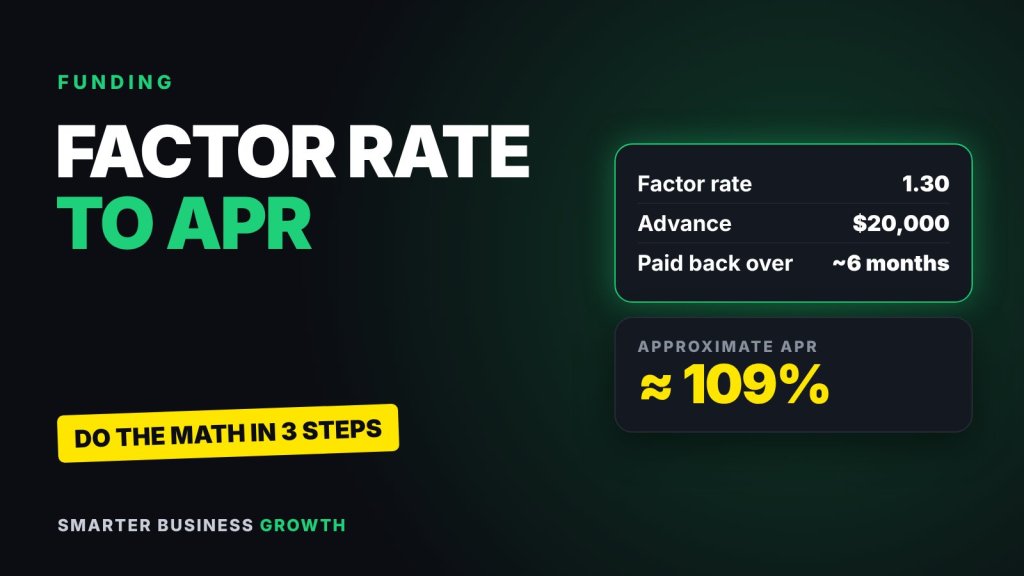
Quick answer: To convert a factor rate to an approximate APR, find the total cost (amount received × factor rate − amount received), figure out how long you have to repay, then account for the fact that you start paying it back right away. A $20,000 advance at a 1.3 factor rate repaid over about six months works out to roughly 109% APR, far higher than the “30%” the factor rate seems to suggest.
Why convert a factor rate to APR at all?
Factor rates and APRs measure cost in completely different ways, so you can’t compare them directly. An APR (annual percentage rate) shows the yearly cost of borrowing, including the time value of money. A factor rate is a flat multiplier with no time built in.
Converting puts an MCA on the same scale as a loan, a line of credit or a credit card, so you can see which offer really costs less.
Step 1: Find the total cost of the money
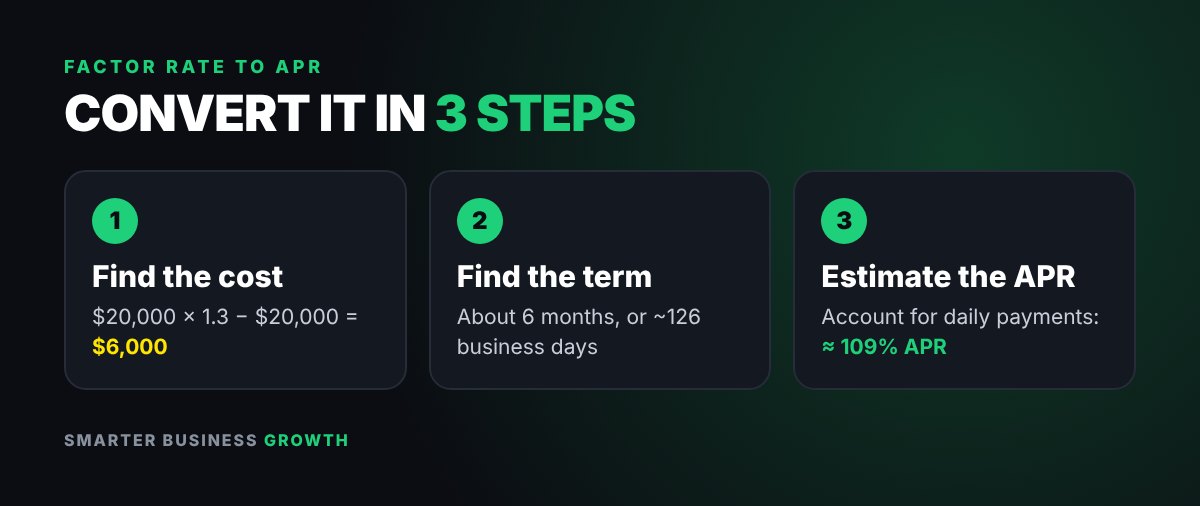
Multiply the advance by the factor rate, then subtract the advance.
- $20,000 × 1.3 = $26,000 total payback
- $26,000 − $20,000 = $6,000 cost
Step 2: Find the repayment term
Ask the provider how long repayment is expected to take. MCAs are usually repaid on business days, roughly 21 per month or about 252 per year. Six months is about 126 business days.
If payments are a percentage of your card sales instead of a fixed amount, the term is an estimate based on your average sales. Slower sales mean a longer term; faster sales mean a shorter one, and an even higher APR.
Step 3: Estimate the APR
A quick shortcut is to divide the cost by the amount received, then annualize it: $6,000 ÷ $20,000 = 30% over half a year, or about 60% a year. But that shortcut understates the cost, because you are paying the balance down every day and never have the full $20,000 for the whole term.
When you account for those daily payments (the same method used to calculate APR on regular loans), the true figure is roughly 109% APR. Any online APR calculator that lets you enter a payment amount and number of payments will give you a close estimate.
Worked examples: same advance, different terms
| Advance | Factor rate | Repaid over | Daily payment | Approx. APR |
|---|---|---|---|---|
| $20,000 | 1.15 | 6 months | ~$183 | ~57% |
| $20,000 | 1.20 | 12 months | ~$95 | ~38% |
| $20,000 | 1.30 | 12 months | ~$103 | ~55% |
| $20,000 | 1.30 | 6 months | ~$206 | ~109% |
| $50,000 | 1.40 | 9 months | ~$370 | ~95% |
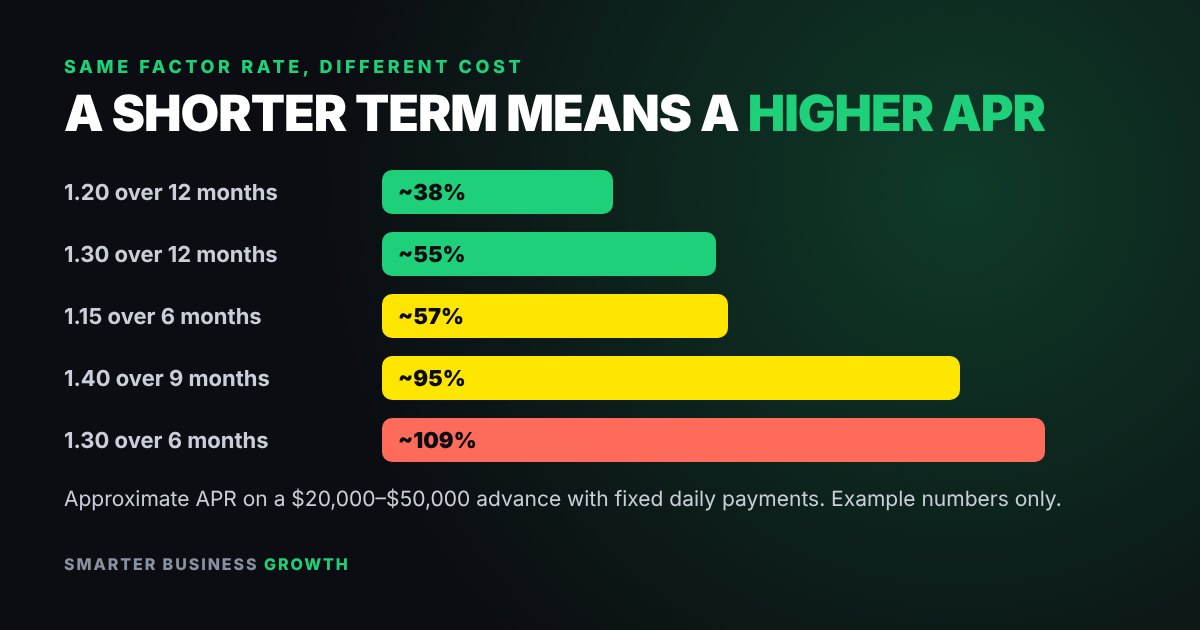
The pattern is clear: the shorter the term, the higher the APR, even when the factor rate stays the same. A 1.3 factor rate costs about twice as much per year when it is repaid in six months instead of twelve.
These are estimates for comparison only, assuming fixed daily payments over about 252 business days a year. Fees taken out of the advance raise the real APR further.
Don’t forget the fees
If a provider charges an origination or underwriting fee that is taken out of your advance, you receive less money but still owe the full payback. For example, a $500 fee on a $20,000 advance means you only receive $19,500, which pushes the effective APR higher still. Always ask for the net amount you will actually receive.
How to compare an MCA with other funding
Once you have an approximate APR, line it up against your other options:
| Option | How it is priced | Typical fit |
|---|---|---|
| Merchant cash advance | Factor rate, fixed cost | Fast, short-term needs with strong card sales |
| Business line of credit | Interest on what you draw | Ongoing or seasonal cash gaps |
| Term loan | Interest over a set term | One-time purchases with a known cost |
| SBA loan | Interest, longer terms | Larger needs when you have time to apply |
Our guide to business line of credit vs loan explains when each one fits, and the SBA’s loan programs page lists government-backed options worth checking.
Common mistakes when comparing offers
- Comparing a factor rate to an interest rate directly. 1.3 is not the same as 30%.
- Using the shortcut and stopping there. It can understate the true cost by almost half.
- Ignoring the payment schedule. A daily payment hits cash flow very differently from a monthly one.
- Forgetting fees that reduce the amount you actually receive.
- Looking at cost alone. Speed, flexibility and what you can comfortably repay matter too.
Convert your own offer: a 5-minute worksheet
Grab your offer and fill in these blanks. You will have a reliable comparison number in a few minutes.
- Amount you actually receive (after any fees): $______
- Total payback: $______
- Payment amount and frequency: $______ per day / week
- Number of payments: ______ (total payback ÷ payment amount)
- Enter those into an APR calculator to get your estimated APR: ______%
Do this for every offer you receive, including loans and lines of credit, and write the results side by side. The cheapest offer is the one with the lowest APR that you can still repay comfortably on a slow week.
When can an MCA still make sense?
A high APR doesn’t automatically rule an advance out. It can be a reasonable tool when:
- You have a short-term, clearly profitable opportunity, like a large order you can fill and get paid for quickly.
- Your card sales are strong and steady enough to absorb daily payments.
- You have compared at least two or three alternatives and the faster option is worth the extra cost.
It is usually a poor fit for covering ongoing losses, paying off another advance, or any need where the money won’t clearly earn back more than it costs.
Get the free Funding Playbook
See how to read any funding offer, what lenders look for and which red flags to walk away from. It’s sent straight to your inbox.
Frequently asked questions
Why don’t MCA providers quote an APR?
Because an MCA is usually structured as a purchase of future sales rather than a loan, many providers aren’t required to show an APR. Some states now require cost disclosures for commercial financing, so you may see an estimated APR on newer offers.
Is a high APR always bad?
Not always. If a short-term advance helps you take on a profitable job you would otherwise miss, the cost may be worth it. The key is knowing the true cost and being sure the return is bigger than the price.
What’s the fastest way to estimate APR?
Use an online loan APR calculator: enter the amount you receive, the payment amount and the number of payments. It will give you a close estimate in seconds.
Can I negotiate a factor rate?
Sometimes. Stronger bank statements, more time in business and competing offers all give you leverage. It never hurts to ask whether a lower rate or a longer term is possible.
Want more quick wins? Follow Smarter Business Growth on YouTube, Instagram, TikTok and Pinterest for daily tips.
Educational content only. Smarter Business Growth is not a lender, and this is not financial or legal advice. Rates, terms and approval depend on the lender and your business.
ABOUT THE AUTHOR
Ellard Thomas, MBA
Ellard is the founder of Smarter Business Growth and a business consultant with 20 years of experience helping small business owners grow, from getting customers to understanding funding.
Watch Smarter Business Growth on YouTube · Follow @smarterbusinessgrowth on Instagram


Leave a Reply