By Ellard Thomas, MBA · Smarter Business Growth
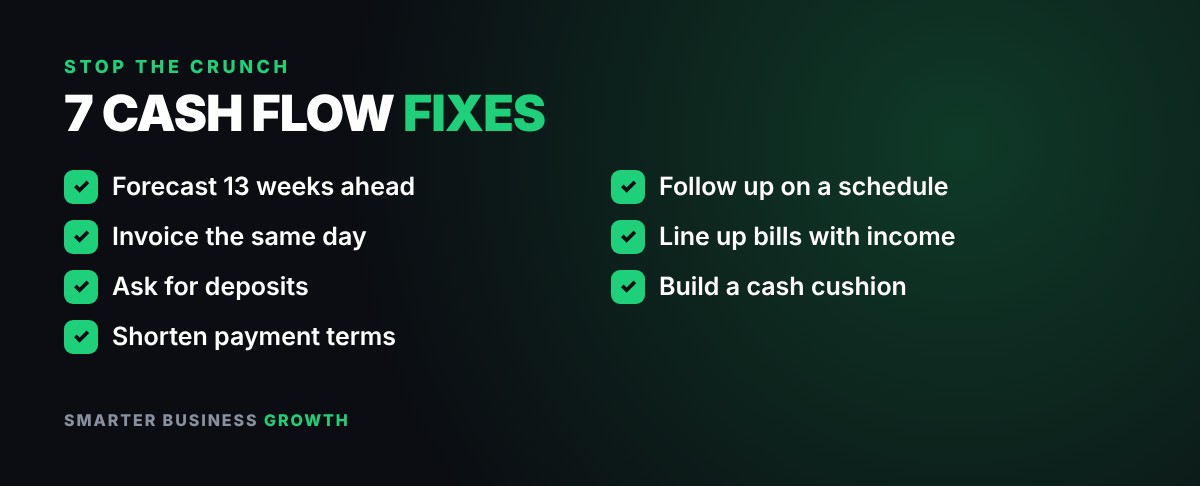
Quick answer: Cash flow is the timing of money in and money out. Most cash crunches happen because bills come due before customers pay, not because the business is losing money. To fix it, forecast your cash 13 weeks ahead, invoice the same day, ask for deposits, shorten payment terms, follow up on late invoices on a schedule, line up your bills with when money comes in, and build a cash cushion.
In this article
Why do profitable businesses run out of cash?
Profit and cash are not the same thing. Your profit and loss statement can show a good month while your bank account runs dry, because the money you earned hasn’t arrived yet. The gap between paying for the work and getting paid for it is called a cash gap.
The most common causes are simple:
- Slow-paying customers. You did the job weeks ago, but the invoice is still open.
- Upfront costs. Payroll, materials and fuel are paid before the customer pays you.
- Growth. More jobs mean more costs up front, so a busy season can squeeze cash harder than a slow one.
- Lumpy bills. Insurance, taxes and loan payments land in big chunks.
- No cushion. One slow month or one late customer leaves nothing to fall back on.
The good news: most of these are timing problems, and timing can be fixed.
7 cash flow fixes to stop the crunch
1. Forecast your cash 13 weeks ahead
List the cash you expect to come in each week and what has to go out: payroll, rent, suppliers, loan payments and taxes. Thirteen weeks is about one quarter, which is far enough ahead to see a crunch coming while there’s still time to act. A simple spreadsheet works fine. Update it every Monday with real numbers.
2. Invoice the same day
Every day you wait to send an invoice is a day added to your cash gap. Send it the day the job is done, from your phone if you have to. Make it easy to pay with a clear due date and a payment link, card or bank transfer.
3. Ask for deposits
For bigger jobs, ask for part of the price up front, such as 25% to 50%, to cover materials and labor. It’s common in many trades, and customers who expect to pay usually don’t mind when you explain it plainly. For ongoing work, consider billing in stages instead of all at the end.
4. Shorten your payment terms
If your invoices say “net 30,” try net 15 or due on receipt for new customers. Shorter terms mean money arrives sooner. For larger clients who insist on longer terms, factor that wait into your price.
5. Follow up on late invoices on a schedule
Don’t wait until you’re short to chase money. Use a simple rhythm: a friendly reminder a few days before the due date, a check-in on the due date, and a firm, polite follow-up a week later. Many accounting tools can send these reminders for you.
6. Line up your bills with when money comes in
Ask your suppliers for longer terms, or move bill due dates closer to when your customers usually pay. If most of your income arrives at the end of the month, a bill due on the 1st is a problem; the same bill due on the 30th may not be.
7. Build a cash cushion
Move a small, set percentage of every deposit into a separate savings account and leave it alone. Many owners aim for a cushion that covers one to three months of essential costs over time. Start small: even 3% to 5% of each deposit adds up.
The U.S. Small Business Administration’s guide to managing your business finances is a good plain-English companion to these steps.
Worked example: closing a landscaper’s cash gap
Jordan runs a 4-person landscaping company. In a busy month he bills $40,000 in jobs, but he invoices when each job is finished and his customers pay on net-30 terms, so most of the money arrives around day 35.
Meanwhile, his costs don’t wait:
| Cost before the first invoice is paid | Amount |
|---|---|
| Payroll (two pay periods) | $12,000 |
| Fuel and supplies | $8,000 |
| Truck payment | $1,200 |
| Total going out first | $21,200 |
That’s a $21,200 cash gap, even though the month is profitable on paper. Here’s what Jordan changed:
- He asks for a 30% deposit on jobs over $1,000. On $40,000 of work, that brings in about $12,000 up front.
- He sends every invoice the same day, on net-15 terms instead of net 30.
- He moves 5% of every deposit into a separate cushion account.
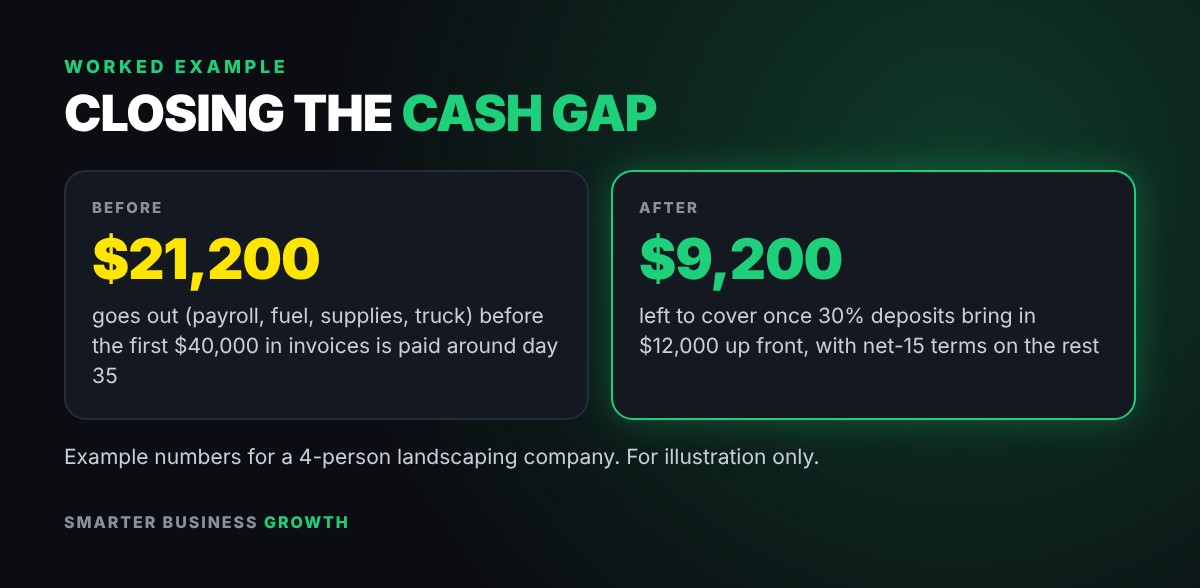
With deposits covering $12,000 of the costs, the gap drops to about $9,200, and the rest of the money arrives weeks sooner. Over a few months the cushion account grows, so the next slow-paying customer is an inconvenience, not an emergency.
Example numbers only. Your costs, terms and timing will be different.
When does financing make sense for a cash gap?
Sometimes a gap is bigger than these fixes can close in time, such as a large job that needs materials up front or a seasonal slowdown. That’s when short-term financing can help, as long as the cost is clear and the money pays for itself.
- A business line of credit often fits recurring cash gaps, because you draw only what you need and pay it down when customers pay. Our guide to business line of credit vs loan explains the difference.
- A merchant cash advance is fast but can be very expensive. Before you sign one, see merchant cash advance vs business loan and how to convert a factor rate to APR.
- Borrowing to cover a gap you haven’t fixed usually makes the next gap bigger. Fix the timing first, then borrow only for what’s left.
Small business cash flow: FAQ
What is cash flow in a small business?
Cash flow is the money coming into and going out of your business over a period of time. Positive cash flow means more came in than went out. It’s different from profit, which counts sales when they’re earned, not when the cash arrives.
What is the biggest cause of cash flow problems?
For many small businesses, it’s timing: paying costs before customers pay. Slow-paying customers, upfront costs and fast growth are the usual culprits.
How much cash should a small business keep on hand?
Many owners aim for one to three months of essential expenses, built up over time. The right amount depends on how steady your income is and how quickly customers pay.
How can I improve cash flow fast?
Send any unsent invoices today, follow up on overdue ones, ask for deposits on new jobs, and talk to suppliers about due dates. Those steps can bring money in sooner without borrowing.
Is a cash flow forecast hard to make?
No. A simple spreadsheet with one column per week, money expected in, money going out and the running balance is enough. Update it weekly and it gets more accurate over time.
Want more quick wins? Follow Smarter Business Growth on YouTube, Instagram, TikTok, Pinterest and LinkedIn for weekly lessons.
Educational content only, not financial advice. Smarter Business Growth is not a lender. Examples are for illustration.
ABOUT THE AUTHOR
Ellard Thomas, MBA
Ellard is the founder of Smarter Business Growth and a business consultant with 20 years of experience helping small business owners grow, from getting customers to understanding funding.
Watch Smarter Business Growth on YouTube · Follow @smarterbusinessgrowth on Instagram


Leave a Reply